Why Solar and Data Centers Now Share a Roadmap
For most of the last decade, Algeria’s renewable-energy programme and its digital-infrastructure plans were discussed in separate documents, by separate ministries, with separate timelines. That has changed. The convergence is now explicit: Sonelgaz’s solar build-out and the growing footprint of Algerian cloud and data-center operators have become a single strategic conversation about how the country powers its AI-era infrastructure without locking in decades of new gas consumption.
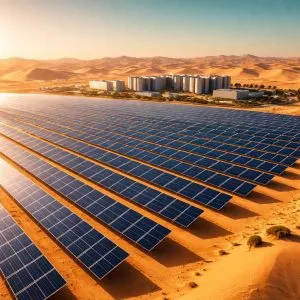
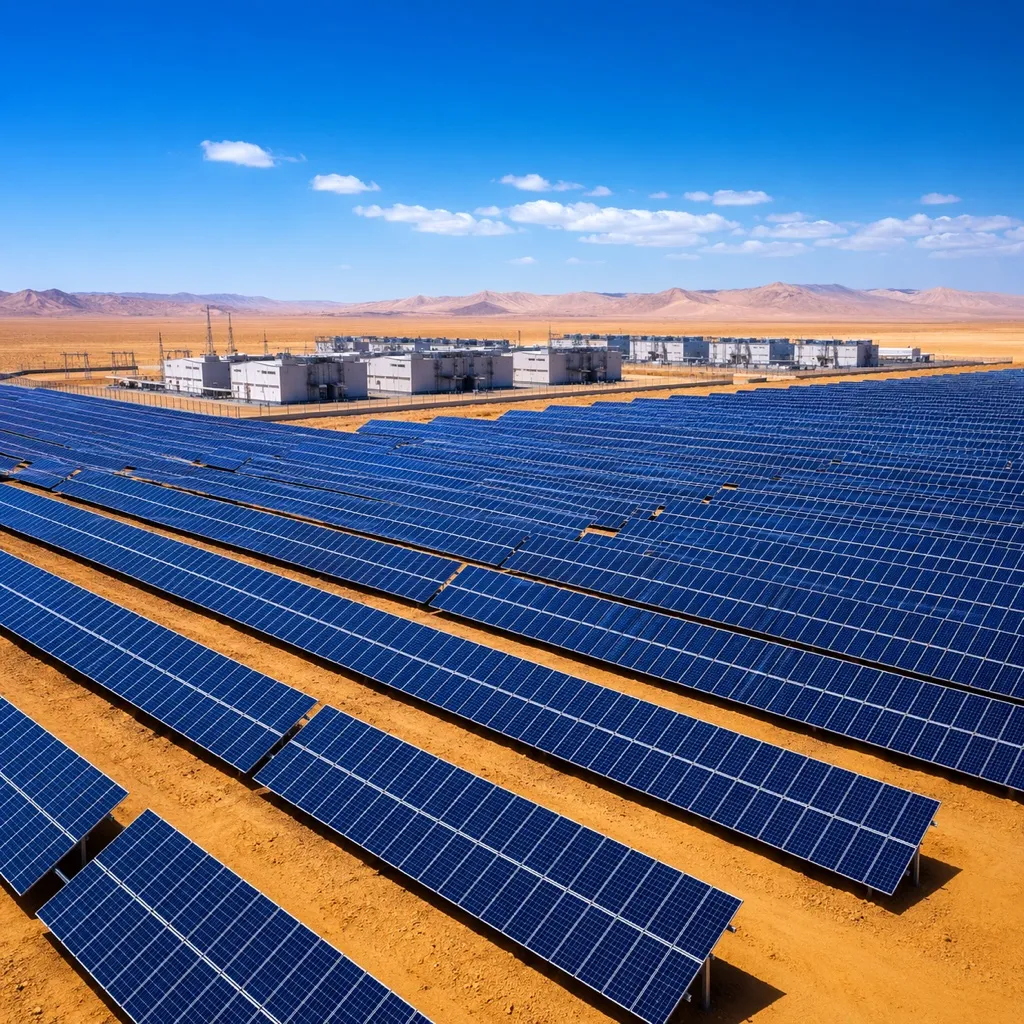
The pivot point of 2026 is the commissioning of 1,480 MW of solar capacity across nine photovoltaic plants, scheduled to come online by August. The installations span El-Oued, Ouled Djellal, Biskra, El-M’Ghair, Abadla, and M’Sila, with the M’Sila site anchoring the broader Solar 1000 programme that Sonelgaz and Sonatrach launched in partnership in early 2024. The roadmap is part of a strategic revision that targets roughly 10 GW of renewables by 2030 and 15 GW by 2035 — scaled down from earlier headline figures but still transformational in operational terms.
The M’Sila Role in the Solar 1000 Programme
The Solar 1000 project covers five provinces, with individual plant capacities ranging from 50 to 300 MW. M’Sila, located in Algeria’s central high plateau, is one of the highest-irradiance sites in the programme and sits within convenient transmission distance of both the northern industrial corridor and the southern computing-cluster strategy that Oran and Ouargla have been anchoring.
Beyond Solar 1000, a second call for tenders launched in 2023 covers 15 additional solar farms with capacities between 80 and 220 MW, targeting a further 2,000 MW. Sonelgaz is also finalising contracts with 19 national and international firms for 20 additional photovoltaic plants as part of the sector’s sustained expansion. The cumulative effect is a pipeline of 6,000 MW to be installed between 2023 and 2027, with M’Sila’s contribution specifically positioned to feed the central-Algeria industrial-digital cluster.
Tendla in El-M’Ghair (93% complete as of early 2026) and El-Ghrous in Biskra (86% complete) are the first of the new plants expected to hit commercial operation. The build progress rate matters because it sets a realistic horizon for when data-center operators can start signing long-term power-purchase agreements against specific renewable assets rather than the grid-average mix.
Where Algeria Fits in Africau2019s Green Data-Center Build-Out
Africa’s data-center market was valued at 3.49 billion US dollars in 2024 and is projected to reach 6.81 billion by 2030, growing at 11.79% annually. Capacity demand is forecast to hit 2 GW by 2030, up from a much smaller base. South Africa leads the continent: Teraco started building a 120 MW solar PV plant in the Free State in late 2024 to power its data centres from 2026, and Africa Data Centres together with Distributed Power Africa is deploying a 12 MW solar farm dedicated to data-centre load. Kenya’s Naivasha geothermal zone is hosting a 100 MW green data-centre project backed by a 1 billion US dollar investment by Microsoft and G42.
Algeria is now stepping into that conversation with a distinct advantage profile, driven by a combination of four factors.
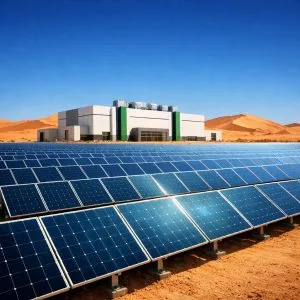
The first is the national renewable programme itself. When 1,480 MW comes online in 2026 and a further 1,500 MW is added annually between 2027 and 2030, the grid-mix carbon intensity drops materially, which improves the environmental profile of any cloud or colocation facility operating in-country. This matters for European and African customers with sustainability reporting obligations.
The second is the SCADA modernisation Sonelgaz is implementing through 2026, which will make Algeria the first North African country to deploy this generation of grid-control technology. Modern SCADA is the precondition for running renewable-heavy grids at scale, matching variable generation with variable loads — including the spiky, high-density workloads of AI-era data centres.
The third is Huawei’s cloud footprint. The Cairo Cloud Region covering 28 African countries (Algeria included) combined with the Huawei Cloud Stack programmes already running at Sonatrach and Algeria Telecom has created the first layer of a regional cloud backbone, and the December 2025 Yassir-Huawei partnership has added an application tier. A solar-backed grid increases the case for adding an Algerian cloud region in the medium term.
The fourth is hydrocarbon economics. Algeria runs on subsidised gas, and for years that suppressed the relative commercial case for solar. But the country’s gas exports are a strategic asset for European diversification, and every megawatt powered by solar domestically frees up gas for export. That turns the solar programme into a fiscal-policy lever as well as an environmental one.
Advertisement
The Compute Side: What Would Actually Run
An AI Supercomputing Centre is under construction in Oran, with GPU clusters destined for researchers, startups, and academia. The centre is the first named, named-location large-scale compute facility publicly planned in Algeria, and its power profile (continuous, high-density, water-cooled) is exactly the kind of load that benefits from a renewable-heavy nearby grid.
Beyond the Oran centre, the medium-term compute demand splits into three buckets. First, hyperscaler-style edge deployments: smaller Huawei or AWS-adjacent nodes serving Algerian government and enterprise workloads from local regions to satisfy data-residency requirements. Second, sovereign colocation: facilities run by Algerie Telecom, Sonelgaz subsidiaries, or defence-sector operators for sensitive workloads, already beginning to consolidate. Third, hyperscale-adjacent AI training: smaller than European or Gulf peers in the near term, but positioned to grow as the Huawei vocational-diploma programme (launching September 2026) supplies trained operators.
The common thread is that all three need reliable, increasingly-green baseload. With 2.6 GW of renewable capacity under construction and a 10 GW interim target by 2030, Algeria can plausibly commit that any new data-centre building opened after 2028 will draw from a grid mix where renewables dominate the marginal unit of consumption.
Sustainability as a Commercial Argument, Not Just an Environmental One
Global cloud and enterprise customers are being asked to report emissions from their third-party infrastructure under frameworks like the EU CSRD and emerging African reporting standards. An Algerian data-centre that can point to a specific solar PPA with a named plant in M’Sila or Biskra is measurably more attractive than one that can only show the national-average grid mix.
This is the same logic that has driven Teraco’s South African solar strategy, Africa Data Centres’ partnership with Distributed Power Africa, and the Kenya-Microsoft-G42 Naivasha deal. It is also the logic that has underpinned Singapore’s decade-long investment in grid renewables as a precondition for maintaining its leadership in regional data-centre hosting.
Algeria’s opportunity is to be the Maghreb’s equivalent: a country with cheap land, strong solar irradiance, a fibre backbone (140,000 km deployed, 2.5 million FTTH subscribers as of September 2025), and a sovereign-cloud playbook already running with Huawei. The 2026 solar commissioning is not yet, on its own, enough to close that gap with South Africa or Kenya. But it is the largest single year of renewable additions in Algeria’s history and the first concrete step toward a grid that can compete on sustainability.
What to Watch
Three signals will confirm whether the alignment sticks.
First, the first Algerian-domiciled solar PPA signed by a data-centre operator. Whether it comes from Algeria Telecom’s own facility programme, a Sonelgaz subsidiary, or a private colocation player, that signature marks the point at which the solar programme has crossed from public-policy statement into commercial underpinning for digital infrastructure.
Second, the Oran AI Supercomputing Centre’s declared power contract. Publishing the procurement terms (whether from grid average or a specific solar allocation) will set the template for the next generation of Algerian compute investment.
Third, regional customer traction. If a European or MENA enterprise cites Algerian solar-backed cloud capacity in its sustainability report within 2027-2028, the commercial reframing is complete. Until then, M’Sila and the wider Solar 1000 build-out remain the enabling layer — quietly reshaping what Algerian digital infrastructure can credibly sell.
Frequently Asked Questions
How much solar capacity is actually coming online in 2026?
1,480 MW across nine photovoltaic plants by August 2026, including major installations at M’Sila, Tendla in El-M’Ghair (93% complete), and El-Ghrous in Biskra (86% complete). The wider pipeline targets 6,000 MW between 2023 and 2027.
Why does Algerian solar matter for data-centre sustainability specifically?
European customers under CSRD and emerging African reporting standards need to disclose emissions from third-party infrastructure. A data-centre tied to a named solar PPA is measurably more attractive than one citing grid-average mix. Teraco in South Africa and Africa Data Centres have already built this playbook.
How does Algeria compare with South Africa and Kenya on green data-centres?
Each country plays to its own strengths. Teraco is building 120 MW of PV for its data-centres and the Kenya-Microsoft-G42 Naivasha project is a 100 MW geothermal AI facility. But Algeria’s 2026 commissioning plus the Oran AI Supercomputing Centre is the first credible step toward Maghreb leadership.
Sources & Further Reading
- Nine solar plants to go online in Algeria in 2026 — Renewables Now
- Algeria to commission 1.48GW of solar capacity by August — ESI-Africa
- Solar 1000: Algeria commits to producing 2,000 MW of green electricity — Trends N Africa
- Algeria SCADA Upgrade: Essential Grid Modernization by 2026 — PVknowhow
- Data Centres in Africa 2026 Economic Report — Africa Data Centres Association
- Development of solar energy: a new turning point for Algeria — Africa Energy Portal