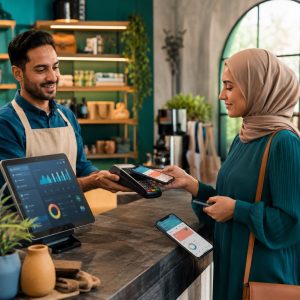
Financial services are disappearing — not going away, but becoming invisible. When a SaaS platform offers instant invoice financing at checkout, when an e-commerce marketplace provides buyer protection insurance without a separate policy, when a logistics app extends working capital to its drivers — that is embedded finance. The financial transaction happens, but no one visits a bank.
In 2026, this trend has moved from experiment to infrastructure. The global embedded finance market is projected to reach $156 billion in revenue this year, growing at a CAGR of 23.84% and on track to surpass $228 billion by 2028 and $454 billion by 2031. What began as consumer-facing payment buttons is now reshaping enterprise procurement, supply chain financing, and platform economics.
Payments Lead, But the Mix Is Shifting
Embedded payments remain the largest segment, accounting for 43.68% of market share in 2025 and maintaining dominance in 2026. The integration of native checkout, in-app wallets, and card-issuing capabilities has become table stakes for any platform with transaction volume. Companies that do not offer seamless payment at point of interaction lose users to those that do.
But the growth frontier has moved beyond payments. Embedded lending — credit products offered at the moment of need, within non-financial platforms — is expanding rapidly. When a B2B marketplace offers net-30 terms to a buyer at checkout, scored in real-time by an AI credit model using platform transaction data, that is embedded lending replacing traditional trade credit.
Embedded insurance is another fast-growing category. Platforms that sell electronics, travel, or vehicles increasingly offer protection products at the point of purchase, underwritten by insurance partners but branded and integrated by the platform. The customer never leaves the buying flow.
The B2B Inflection Point
The most significant structural shift in 2026 is the explosion of embedded finance in B2B contexts. According to PYMNTS research, 54% of US B2B platforms report that embedded finance has already improved their revenue. The B2B embedded payments market is projected to nearly quadruple from $0.7 trillion to $2.6 trillion, with revenues growing proportionally from $1.9 billion to $6.7 billion.
This makes sense when you consider the friction in traditional B2B payments. Enterprise purchasing historically involves purchase orders, invoices, net-30 or net-60 terms, manual reconciliation, and separate banking relationships for credit. Embedded finance collapses this stack: the buyer gets credit at checkout, the seller gets paid immediately, the platform earns a fee, and an API handles the complexity.
The B2B embedded finance market stood at approximately $4.1 trillion in 2026 and is projected to reach $15.6 trillion by 2030. For platform companies, this represents an entirely new revenue layer — financial services margins on top of marketplace or SaaS fees.
Advertisement
The Technology Stack Enabling It
Embedded finance depends on a modular technology stack: banking-as-a-service (BaaS) providers supply the regulated infrastructure, APIs connect platforms to financial capabilities, and AI models handle real-time credit decisions, fraud detection, and personalization.
Key enablers include companies like Stripe Treasury, Unit, Galileo, and Marqeta that provide the plumbing. A SaaS company with zero banking experience can now offer its customers deposit accounts, card issuance, lending, and insurance — all through API integrations that take weeks, not years, to implement.
The regulatory landscape is evolving to accommodate this model. Financial regulators in the US, EU, and UK are developing frameworks for “platform finance” that recognize the role of technology intermediaries while maintaining consumer protection. The challenge is balancing innovation speed with regulatory oversight.
Retail and E-Commerce Lead Adoption
Retail and e-commerce platforms captured the largest share of embedded finance adoption in 2025, driven by the foundational need to process payments and extend credit at checkout. But adoption is spreading rapidly to logistics, healthcare, real estate, and professional services.
The economics are compelling. A platform that adds embedded lending generates 15-30% more revenue per user through interest income and origination fees. Embedded insurance adds another 5-10% through premium commissions. These incremental revenue streams compound: a platform with payments, lending, and insurance embedded into its user experience can derive 40-60% of its revenue from financial services — transforming it from a technology company into a financial services company without applying for a banking license.
Risks and Challenges
Embedded finance is not without risk. Concentration of financial services within technology platforms raises concerns about systemic risk, data privacy, and fair lending. When a single platform acts as marketplace, lender, insurer, and payment processor, the failure modes multiply.
Credit risk is particularly acute in the B2B segment, where loan sizes are larger and default consequences more severe. Platforms extending credit based on transaction data face the same vintage effects and economic cycle sensitivity as traditional lenders — but often with less experience managing portfolio risk.
Regulatory arbitrage is another concern. Embedded finance providers that operate through bank partners sometimes fall into gaps between fintech regulation and banking supervision, creating compliance vulnerabilities.
Frequently Asked Questions
What is embedded finance?
Embedded finance is the integration of financial services — payments, lending, insurance, banking — directly into non-financial platforms and applications. Instead of visiting a bank, users access financial products seamlessly within the apps they already use, such as e-commerce marketplaces, SaaS platforms, or logistics applications.
Why is B2B embedded finance growing so fast?
Traditional B2B payments involve significant friction: purchase orders, invoices, manual reconciliation, and separate banking relationships. Embedded finance collapses this complexity by offering credit, payment, and financing at the point of transaction within platform workflows. 54% of US B2B platforms report revenue gains from adding embedded financial services.
How big is the embedded finance market in 2026?
The global embedded finance market is projected to reach approximately $156 billion in revenue in 2026, growing at a 23.84% CAGR. Payments lead with 43% market share, followed by embedded banking, lending, and insurance. The market is on track to surpass $228 billion by 2028 and $454 billion by 2031.
Sources & Further Reading
- Embedded Finance Market Anticipated to Surpass $228B by 2028 — Juniper Research
- Embedded Finance Pays Off for 54% of US B2B Platforms — PYMNTS
- The Next Frontier: Why Embedded B2B Finance Is Breaking Out in 2026 — Galileo
- Embedded Finance Market to Surpass $454 Bn by 2031 — Mordor Intelligence
- Embedded Finance Report: Thriving in the New Value Chain — Bain & Company